Home / Truck and trailer financing
Financing from people who know what a truck actually costs to run.
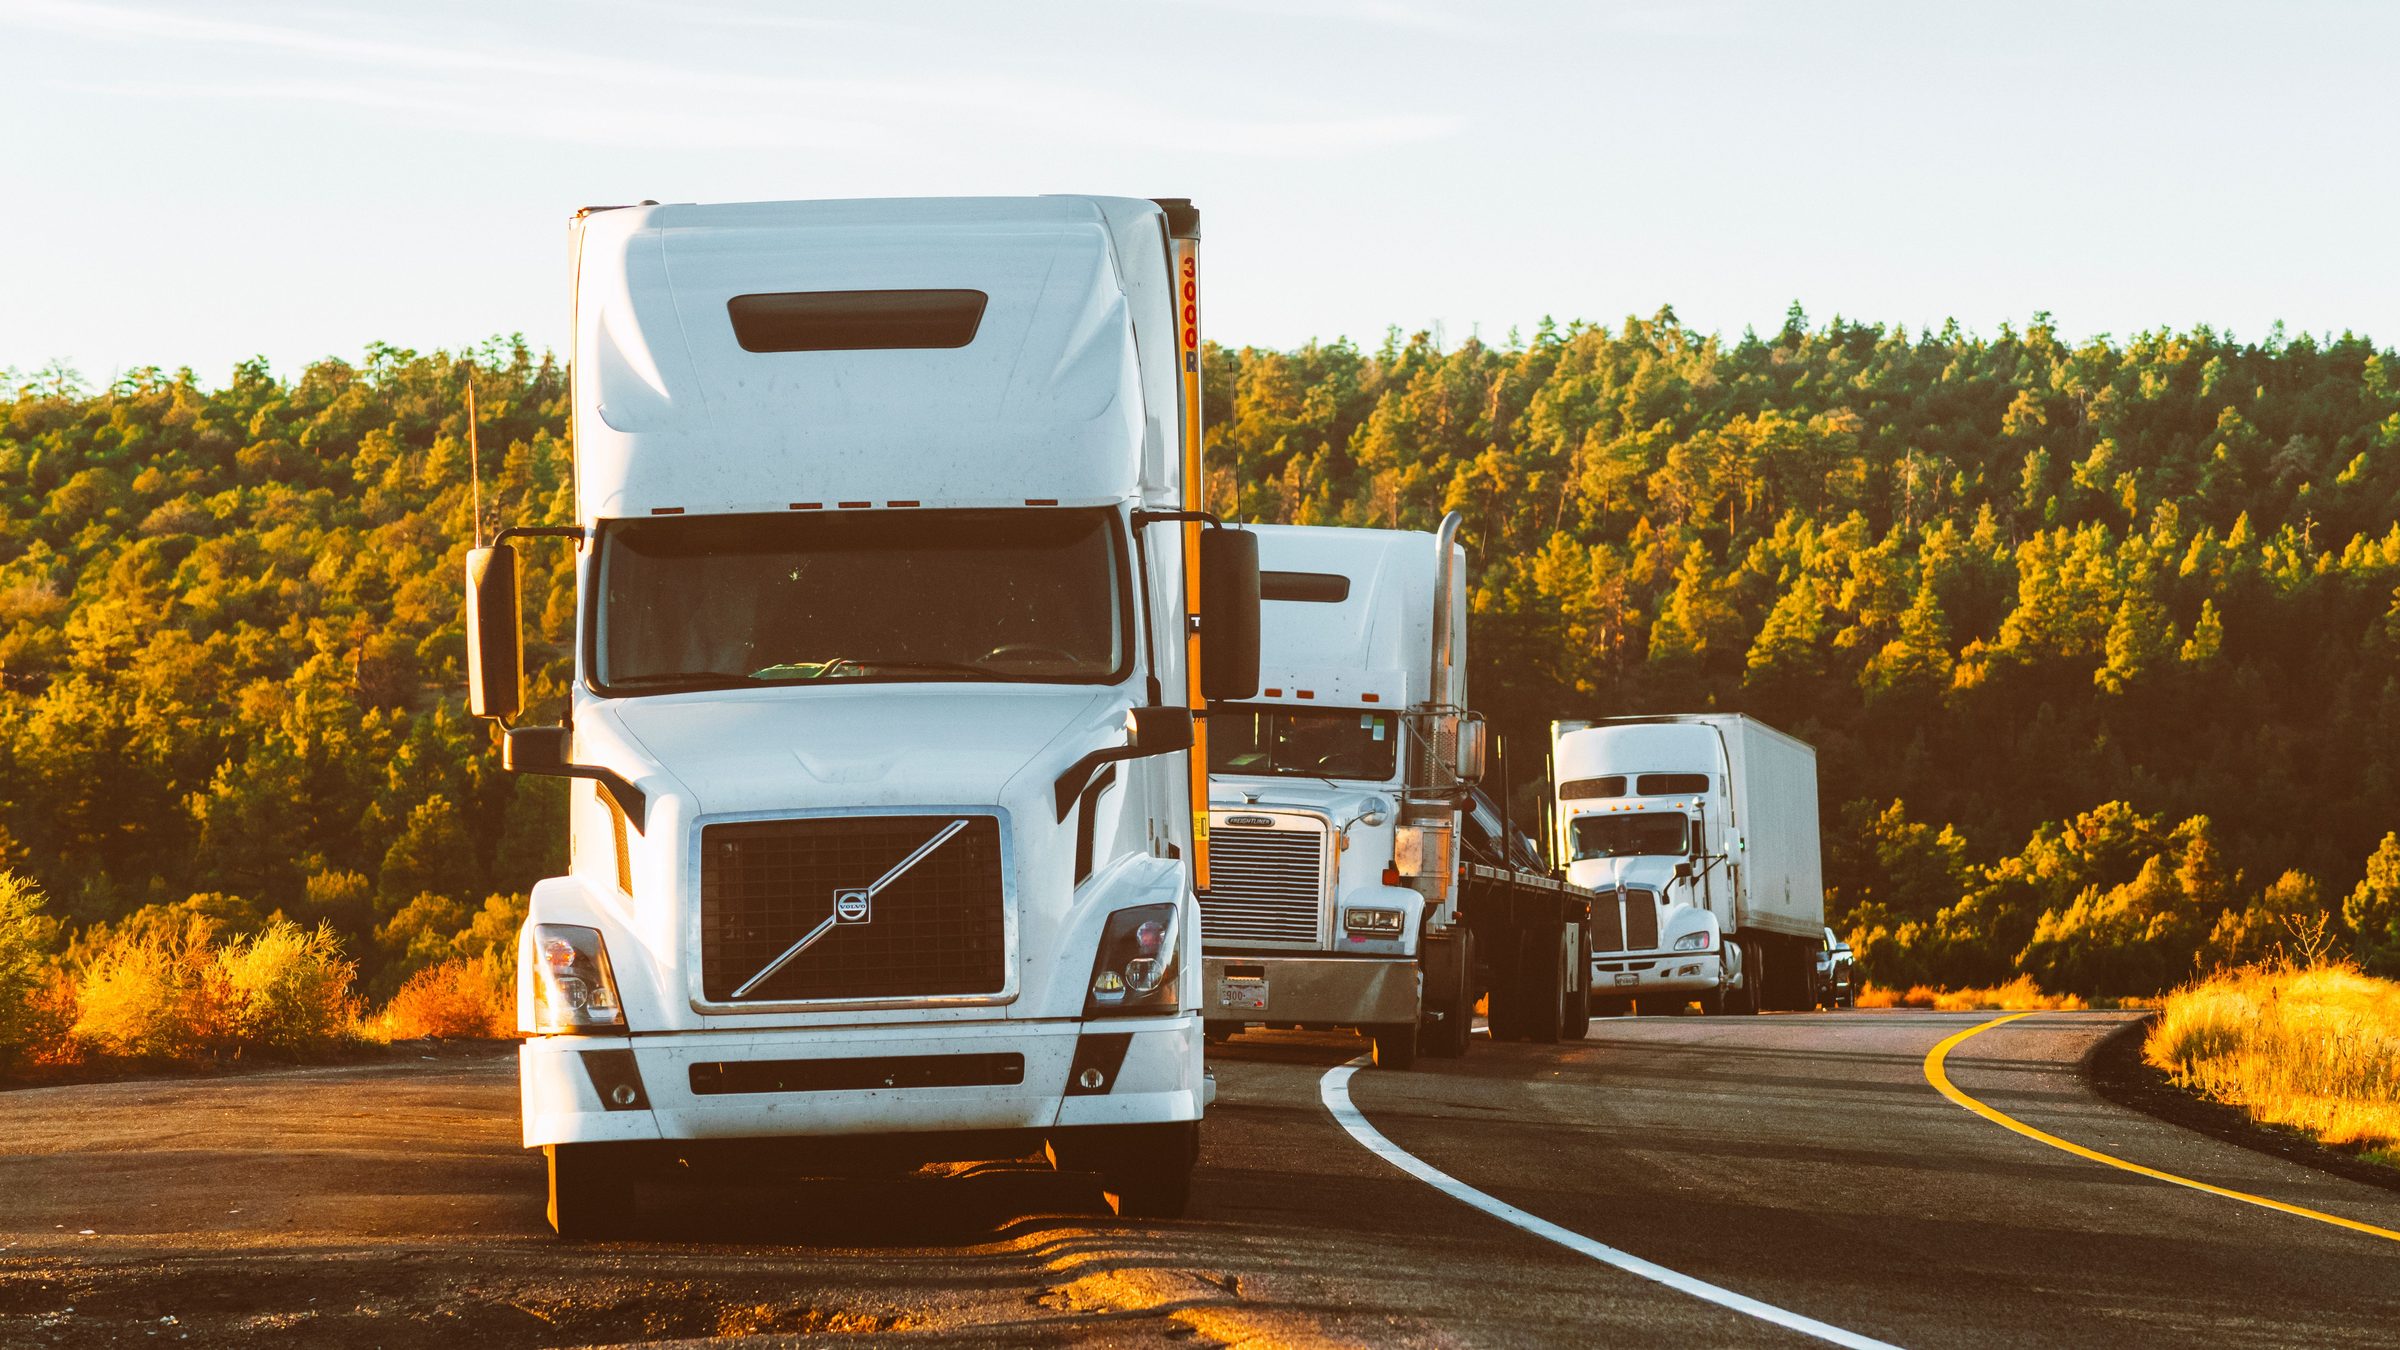
Tractors, trailers and the equipment an owner operator runs on. New and used, first truck or tenth.
What we finance.
We work with more than three truck lenders. They generally look for a credit score of 660 or better and three years of financials or industry experience. Exact terms depend on the lender and on the file.
Tractors
Day cabs and sleepers, new off the lot or used off another carrier. Age matters less than people expect. What an older truck changes is the term you can get, not whether it can be financed at all.
Trailers and equipment
Dry vans, reefers, flatbeds and the attachments that go with the work. All three are in appetite.
Refinancing what you already run
We can pay off a truck loan you already have, whether it sits with another lender, a private lender or the seller. Subject to program guidelines and approval.
How the age of the truck sets the term.
A truck that holds its value can be financed. What its age changes is how long the loan can run. These are the usual brackets our lenders work to, and a specific lender may set them differently.
Under 5 years old
Up to 72 months.
6 to 8 years old
Up to 60 months.
9 to 10 years old
Up to 48 months.
Over 10 years old
Up to 36 months.
There is no mileage cutoff on its own. What matters is what the truck is worth, which is why the spec sheet or listing is the first thing we ask for. Terms shown are the longest generally available in each bracket and are not an offer of credit.
You should not have to explain your own industry to your lender.
We finance tractors and trailers all year round, for owner operators and small fleets across Indiana. So when you tell us the truck is going on someone else’s authority for the first year, or that your statements look thin because you only ran nine months, nobody here needs that spelled out.
How an equipment file runs here.
Four steps, and you hear from us at each one. We do not put a number of days on any of them, because the honest answer depends on the truck, your file and the lender.
Questions before you start?
(317) 620-4100
Tell us about the truck
Year, make, mileage, and who you are buying it from. A dealer sale and a private sale are not treated the same way, and that changes which lenders are worth approaching.
You apply
One secure application. Your documents go up once and are not asked for again halfway through.
We place it
Your file goes to lenders who finance equipment for carriers your size. We tell you what came back and what the real cost of each one is over the term.
The lender funds and you take delivery
We coordinate with the seller and stay on it through funding, so the truck is not sitting while paperwork catches up.
What to have ready.
Have these to hand and the first conversation is a great deal shorter.
- Personal tax returns for the last three years
- Business tax returns for the last three years, if you have them
- If your 2025 return is not filed yet: a 2025 year-end balance sheet, profit and loss, and debt schedule
- The purchase agreement or purchase order for the truck
- A valid government-issued photo identification
- Your CDL, and your MC and DOT numbers if you run under your own authority
- Whether you are buying from a dealer or a private seller